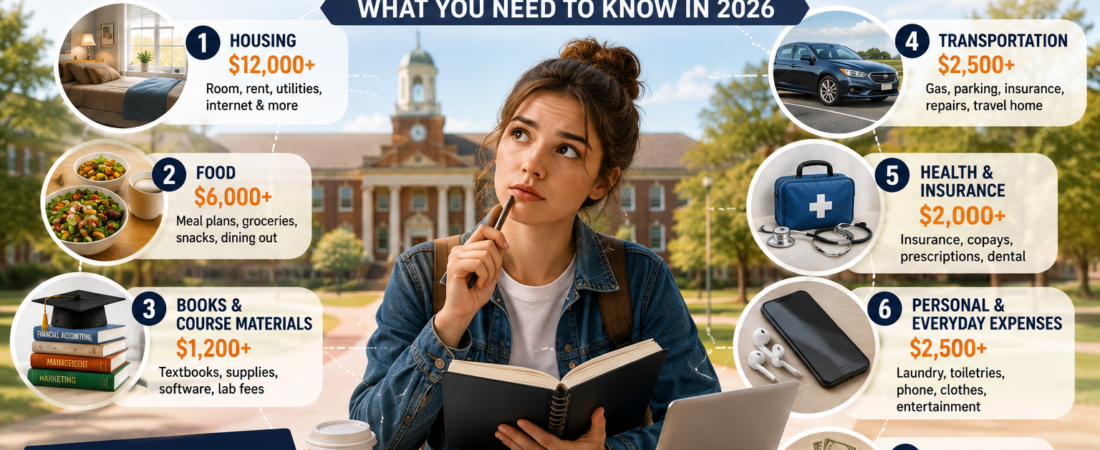
Hidden college costs can make higher education far more expensive than families initially expect. When families think about the cost of college in the United States, tuition is usually the first number they consider. But tuition represents only part of what students may actually spend each year.
That makes sense. Tuition is often the largest number displayed on a university’s website, and it is the figure most frequently discussed when people compare colleges.
But tuition alone does not tell you how much it actually costs to attend college.
A student may receive scholarships or grants that significantly reduce tuition and still discover that the family’s real annual expenses are surprisingly high. Housing, food, transportation, books, health-related charges, technology, and everyday personal expenses can add thousands—or even tens of thousands—of dollars to the annual budget.
That distinction is especially important in the 2025–26 academic year.
According to the College Board, average published tuition and fees for 2025–26 are $11,950 for in-state students at public four-year institutions, $31,880 for out-of-state students at public four-year institutions, and $45,000 at private nonprofit four-year colleges.
But the average total student budgets are considerably higher: approximately $30,990 for an in-state student at a public four-year institution, $50,920 for an out-of-state public university student, and $65,470 at a private nonprofit four-year institution.
So where does the rest of the money go?
Here are seven expenses families can easily underestimate when planning for college in America.
1. Housing Can Change the Entire College Budget
Housing is one of the biggest reasons the true cost of college can be much higher than tuition alone.
Students living in residence halls generally pay room charges directly to their college. Depending on the institution and location, the amount can be substantial.
Moving off campus does not necessarily solve the problem.
An apartment may require:
- Monthly rent
- Security deposits
- Electricity
- Gas
- Water
- Internet service
- Furniture
- Renter’s insurance
- Parking
- Moving expenses
Students living in expensive metropolitan areas can face particularly high housing costs.
There is also an important budgeting mistake families sometimes make: comparing nine months of university housing with twelve months of apartment rent.
A student who signs a 12-month lease may continue paying rent during summer even if classes have ended or the student temporarily returns home.
For families comparing colleges, therefore, asking “What is tuition?” is not enough.
A better question is:
What will housing realistically cost for the entire year?
That calculation can significantly change which college is actually affordable.
2. Food Costs Extend Far Beyond the Dining Hall
Food is another major part of the college budget.
Students living on campus may be required to purchase a meal plan. Depending on the school, meal plans can include a fixed number of meals, unlimited dining, dining credits, or combinations of these options.
But paying for a meal plan does not mean a student will never spend additional money on food.
Students often purchase:
- Coffee
- Snacks
- Bottled drinks
- Restaurant meals
- Delivery food
- Groceries
- Food during school breaks
- Meals while traveling
- Late-night meals when dining halls are closed
Small purchases can become surprisingly expensive when repeated throughout a semester.
For example, spending $12 outside the meal plan three times a week equals more than $1,400 over a 40-week period.
That does not mean students must avoid eating out completely. It means families should recognize that “room and board” may not represent every food-related expense.
One practical strategy is to create a separate monthly food allowance before the semester begins.
Students can then see how much discretionary food spending is actually affordable instead of relying on credit cards or repeatedly asking family members for additional money.
3. Books, Course Materials, and Technology
The traditional image of college expenses includes stacks of expensive textbooks.
Textbooks remain an expense, but today’s academic costs go far beyond printed books.
Depending on the student’s major, courses may require:
- Digital textbooks
- Online homework platforms
- Laboratory materials
- Art supplies
- Engineering equipment
- Calculators
- Software subscriptions
- Printing
- Specialized uniforms
- Professional equipment
- Laptops or tablets
Some courses require access codes that cannot easily be purchased used. Others require software that may only be available through a subscription.
Technology can create an especially uneven expense.
A laptop might last an entire undergraduate career—or fail unexpectedly in the middle of a semester.
Students studying graphic design, engineering, computer science, architecture, video production, or other technology-intensive subjects may also require more powerful and expensive computers than students whose courses mainly involve reading and writing.
Federal Student Aid specifically advises first-time college students to budget not only for tuition, housing, and food but also for equipment, books, supplies, transportation, and personal expenses.
The important lesson is simple:
Academic expenses do not stop after tuition has been paid.
4. Transportation Is Easy to Underestimate
Transportation costs vary dramatically depending on where a student lives and attends school.
A student who lives at home and attends a nearby university may need to budget for:
- Gasoline
- Auto insurance
- Parking permits
- Vehicle maintenance
- Registration
- Repairs
A student attending college far from home may instead face:
- Airline tickets
- Airport transportation
- Train tickets
- Bus fares
- Rideshare services
- Holiday travel
- Shipping personal belongings
Travel becomes especially expensive around Thanksgiving, winter break, and spring break, when millions of people are traveling at the same time.
A family might initially calculate only two round-trip flights per year and later discover that the student also wants or needs to return home for family events, medical appointments, emergencies, internships, or other reasons.
Even students who do not own cars can spend substantial amounts on transportation.
Rideshare trips that cost $15 or $20 may seem insignificant individually, but frequent use can quickly turn them into a meaningful monthly expense.
Transportation should therefore have its own line in a college budget rather than being placed vaguely under “miscellaneous expenses.”
5. Health Insurance and Medical Expenses
Health-related costs deserve special attention because they can be both significant and unpredictable.
Many colleges require students to demonstrate that they have qualifying health insurance. Students without acceptable outside coverage may be enrolled in a university-sponsored health insurance plan.
Families should examine this carefully before the academic year begins.
Having health insurance also does not eliminate medical expenses.
Students may still encounter:
- Deductibles
- Copayments
- Prescription costs
- Dental expenses
- Vision expenses
- Urgent care visits
- Emergency room charges
- Medical transportation
Even routine healthcare can become more complicated when a student attends college far from home.
A family’s regular doctors may be hundreds or thousands of miles away, and the family’s insurance network may work differently in another state.
Before enrollment, families should investigate both the university’s health insurance requirements and their existing insurance coverage.
This is one area where planning ahead can prevent a relatively small health problem from turning into a major financial surprise.
6. Personal and Everyday Living Expenses
College students still have normal everyday expenses.
These may include:
- Laundry
- Toiletries
- Haircuts
- Clothing
- Phone service
- Household supplies
- School organization supplies
- Entertainment
- Club activities
- Gifts
- Social events
Individually, many of these expenses look small.
Together, they can add hundreds of dollars per month.
The challenge is that personal expenses are often invisible when families first compare colleges.
A university may prominently display tuition and housing prices, while the cost of replacing shoes, buying detergent, paying a phone bill, or attending a friend’s birthday dinner never appears on the tuition statement.
This is why families should distinguish between the college bill and the cost of being a college student.
They are not the same thing.
A useful approach is to establish a realistic monthly personal budget and let the student manage it.
This gives students an opportunity to develop financial independence while protecting the family’s larger college budget.
7. Hidden College Costs Nobody Plans For
Finally, every college budget should include an emergency category.
Unexpected expenses are almost inevitable over four years.
A student may need to:
- Replace a broken laptop
- Repair a car
- Fly home unexpectedly
- Move to different housing
- Replace a lost phone
- Purchase required equipment
- Pay an unexpected medical bill
- Take an additional summer course
- Extend college by another semester
The last possibility can be especially expensive.
Families frequently calculate the cost of a bachelor’s degree by multiplying one year’s cost by four.
But not every student graduates in exactly four years.
Changing majors, transferring schools, repeating classes, limited course availability, internships, personal circumstances, or other academic decisions can extend the timeline.
An additional semester can mean another round of tuition, housing, food, transportation, and other expenses.
For that reason, one of the most important financial questions families can ask is not simply:
How much does this college cost per year?
It is:
How much is the entire degree likely to cost?
Sticker Price vs. Net Price: A Critical Difference
There is another reason college costs can be confusing.
The published price is not necessarily what a family actually pays.
Many students receive grants and scholarships.
College Board data show that grant aid substantially reduces tuition costs for many students. For 2025–26, the estimated average net tuition and fees for first-time, full-time in-state students at public four-year institutions is much lower than the published sticker price.
This is why families should avoid rejecting a college solely because its advertised tuition appears high.
A private university with a large sticker price may provide significant institutional grants.
Meanwhile, a lower-priced institution may offer less aid to a particular student.
The number that matters most is the net price after grants and scholarships—not simply the advertised tuition.
Families can use each institution’s net price calculator to obtain an estimate based on their financial circumstances.
However, even net price estimates need to be viewed alongside the other expenses discussed in this article.
Scholarships may help with tuition while families still need to cover transportation, personal expenses, technology, or other costs.
Why College Can Feel More Expensive Even When Tuition Isn’t Exploding
There is an important nuance in the college affordability debate.
It is easy to assume that tuition is rising dramatically every year.
The data tell a more complicated story.
College Board reports that after adjusting for inflation, average published tuition and fees actually declined over the past decade in the public two-year and public four-year sectors. Private nonprofit four-year tuition increased only modestly in inflation-adjusted terms during that period.
Yet families can still feel intense financial pressure.
Why?
Because tuition is only one component of the household budget.
Housing, food, transportation, insurance, technology, and everyday living costs all influence how affordable college feels.
At the same time, families are paying mortgages or rent, groceries, healthcare, utilities, car expenses, and other household bills.
College expenses are layered on top of those existing obligations.
That is why a relatively modest tuition increase can still feel painful.
The broader cost of living matters.
How Families Can Build a More Realistic College Budget
Before choosing a school, families can create a simple annual worksheet.
Start with:
Tuition and mandatory fees
Then add:
Housing
Calculate residence hall charges or actual rent, utilities, deposits, and renter’s insurance.
Food
Include the meal plan plus realistic off-campus food spending.
Books and academic supplies
Consider the student’s specific major.
Technology
Include computers, software, accessories, and possible replacement costs.
Transportation
Calculate local transportation plus travel between school and home.
Health costs
Include insurance premiums when applicable, deductibles, prescriptions, and routine healthcare.
Personal expenses
Create a reasonable monthly allowance.
Emergency reserve
Even a modest emergency fund can help prevent unexpected expenses from becoming credit-card debt.
After calculating the total, subtract grants and scholarships that do not have to be repaid.
That provides a much clearer picture of what the family may actually need to finance.
Ways Students Can Reduce the Real Cost of College
Families do have options.
Students can compare financial aid offers rather than comparing sticker prices alone.
They can also consider:
- Starting at a community college
- Attending an in-state public university
- Living at home when practical
- Applying for outside scholarships
- Buying used or renting textbooks
- Using student discounts
- Choosing lower-cost housing
- Cooking more meals
- Using public transportation
- Working part time when academically manageable
- Completing required courses on schedule
- Taking advantage of free campus resources
None of these strategies works for every student.
The goal is not simply to choose the cheapest college.
The goal is to understand what the student is buying, what the family can realistically afford, and how much debt may be required to complete the degree.
The Bigger Question: What Are You Paying For?
College should ultimately be evaluated as a long-term investment.
Cost matters enormously, but price alone cannot determine value.
Families should also examine:
- Graduation rates
- Academic programs
- Career outcomes
- Internship opportunities
- Financial aid
- Student support
- Location
- Time required to graduate
- Expected borrowing
A school that costs slightly more but enables a student to graduate on time with strong career opportunities could potentially be a better financial choice than a cheaper institution where graduation takes longer.
Likewise, taking on very large amounts of debt for a degree should prompt careful examination of likely earnings and repayment obligations.
The objective is not to find a universally “good” or “bad” price.
It is to understand the relationship between cost, debt, time, and expected value.
Final Thoughts
Understanding hidden college costs before choosing a school can help families build a more realistic budget and avoid unexpected financial pressure. These hidden college costs can vary significantly depending on where a student lives, studies, and travels during the academic year.
The true cost of college in America is much larger and more complicated than the tuition number printed on a university website.
For the 2025–26 academic year, average published tuition and fees range widely depending on institution type, but total student budgets demonstrate how dramatically housing, food, transportation, books, supplies, and other living expenses can change the final price.
Families preparing for college in 2026 should therefore look beyond tuition.
Ask what housing will cost.
Estimate food realistically.
Calculate travel.
Check health insurance.
Budget for technology and academic supplies.
Include personal expenses.
And leave room for the unexpected.
Most importantly, compare the net price and total cost of attendance, not just the sticker price.
A college that appears expensive at first may become affordable after financial aid, while a seemingly inexpensive college can become much more costly after housing and other expenses are included.
Understanding those differences before enrollment can help families make decisions based on real numbers instead of surprises.
Sources
College Board, Trends in College Pricing and Student Aid 2025
College Board — Trends in College Pricing
Federal Student Aid, U.S. Department of Education, 9 Things First-Time College Students Need to Know
Federal Student Aid — First-Time College Students